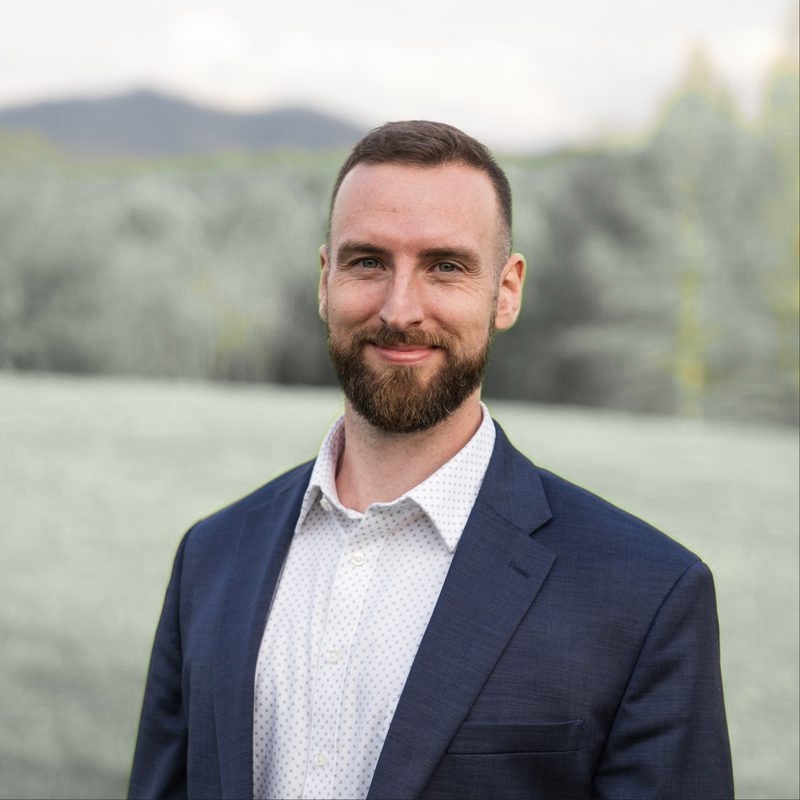
Your Tri-Cities Mortgage Loan Officer
Marine Corps Veteran helping Tri-Cities buyers with VA, FHA, USDA, conventional and refinance loans. I’ll show you what you may qualify for and what it is likely to cost, before you commit to anything.
“He was knowledgeable, responsive, and made the loan process smooth from start to finish.”
“He was professional, responsive, took the time to explain every step clearly, which made the entire process much less stressful.”
“Communication was always prompt, clear, and proactive.”
Find the loan that fits your situation
Most buyers don’t know what they qualify for until someone sits down and shows them. That first conversation is free.
VA Loans
Zero down for eligible Veterans and service members, with no monthly mortgage insurance.
Explore VA loans →First-time friendlyFHA Loans
Lower down payments and flexible credit guidelines for buyers building their footing.
Explore FHA loans →Rural and suburbanUSDA Loans
Zero down in eligible areas, which cover much of the Tri-Cities region.
Explore USDA loans →Solid creditConventional Loans
Flexible terms for buyers with strong credit and stable income. No mortgage insurance with 20% down.
Explore conventional →Current homeownersRefinance
Lower your payment, shorten your term, or access equity, when the numbers make sense.
Explore refinancing →Tennessee helpDown Payment Help
Tennessee programs, including THDA, that may help with a down payment or closing costs.
See your options →A Marine handling your VA loan
I served in the Marine Corps and used the VA home loan benefit myself. If you are a Veteran or active-duty service member, I’ll show you what you’ve earned and how often eligible buyers leave it on the table.
Sam Timlick is a Marine Corps Veteran. He and NFM Lending, LLC are not affiliated with, endorsed by, or sponsored by the U.S. Department of Veterans Affairs or any government agency.
Johnson City’s loan officer who stays in it with you
I live in the Tri-Cities and I’m raising four boys here with my wife. I treat every loan like it’s for my own family.
- Licensed in Tennessee and Virginia
- Direct cell access: call or text me, not a call center
- Honest advice, including when waiting is the smart move
Serving Johnson City, Kingsport, Bristol, Elizabethton, Jonesborough, Greeneville, Blountville, Bluff City, Limestone, Mosheim, Morristown and surrounding communities.
What happens after you call
No obligation and no pressure. Just clarity on where you stand.
We talk through your situation
Your timeline, income, credit questions, and the kind of home you want.
I run your numbers
What you can afford, likely monthly payment, programs you may qualify for, and estimated cash to close.
You get a Loan Estimate
A written federal disclosure showing your estimated rate, payment, and costs.
We close, and I stay in touch
I keep you and your agent updated through closing day, and I’m here afterward.
Do a little homework first
Calculators, local data, and plain-English guides to help you plan.
Mortgage calculators
Local tools, plus links to the calculators provided on NFM Lending’s website.
See all calculators → Market educationRates in context
See how today’s 30-year fixed rate compares with the past year, the past decade, and 1971 to now.
View rate history → GuideFirst-time buyer guide
What to prepare, what to avoid, and which questions to ask your lender in Tennessee.
Read the guide →Tri-Cities housing market
Johnson City
Kingsport
Bristol
Figures as shown in the report’s table; Johnson City and Kingsport reflect the three months ending August 2026. Redfin’s calculations, deemed reliable but not guaranteed. General market information, not personalized advice.
Questions buyers ask every week
Ready to see your options?
No obligation. We’ll go over where you likely stand and which options fit, before you commit to anything.
Prefer to start online? Start your application · stimlick@nfmlending.com · Real estate agent? See how I work with agents